The primary purpose of this newsletter is:
- to review the actuarial valuation information and contribution requirements of the Non-Academic Pension Plan as at Dec. 31, 2025
- to review investments and investment performance of the plan in 2025
Pension plan information
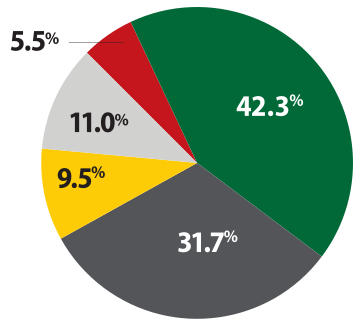
Market value of pension plan assets
as of Dec. 31, 2025
|
Fund
|
2025
|
2024
|
|
| Canadian equities | $22,413,000 | $40,315,000 | |
| Global Equities | $172,544,000 | $172,103,000 | |
| Total Equities | $194,957,000 | $212,418,000 | |
| Bonds | $129,275,000 | $104,824,000 | |
| Real Estate | $38,945,000 | $43,525,000 | |
| Infrastructure | $45,035,000 | $41,164,000 | |
| Total Fixed Income | $213,255,000 | $189,513,000 | |
| Total market value | $408,212,000 | $401,931,000 | |
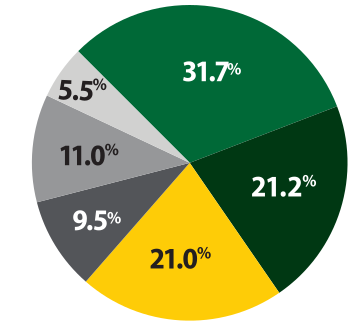
Distribution of assets among investment managers
as of Dec. 31, 2025
|
Fund
|
2025
|
2024
|
|
| PHN Investment | $129,275,000 | $104,824,000 | |
| Harding Loevner | $86,660,000 | $88,157,000 | |
| TDAM Epoch | $85,884,000 | $83,946,000 | |
| TD Greystone Real Estate | $38,945,000 | $43,525,000 | |
| IFM Global Infrastructure | $45,035,000 | $41,164,000 | |
| Connor, Clark and Lunn | $22,413,000 | $40,315,000 | |
Investment performance
The long-term investment goal of the plan is to achieve a minimum annualized rate of return that supports the funded status of the plan. To achieve this goal, the plan has adopted an asset mix that has a bias in favour of equity investments.
The responsibility for investing the assets of the plan has been delegated to six professional investment fund managers with different mandates to ensure adequate investment diversification.
The plan’s return benchmark is a performance standard developed by the investment consultant, Aon. The Board of Governors have approved the benchmark. The investment fund managers of the plan are expected to meet or surpass the benchmark.
Funds
| Investment performance | 2025 | Last four years | Last 10 years |
| Return* | 8.9% | 5.5% | 8.0% |
| Benchmark | 9.9% | 6.4% | 7.8% |
*Gross of fees
Membership data
as of Dec. 31, 2025
Active members
Pensioners and beneficiaries
Other members
deferred, pending transfers, transfer
deficiency holdbacks
Total membership
Your pension plan
You participate in the defined benefit (“DB”) pension plan. When you retire, you receive a set monthly pension payment for the rest of your life.
Financial position
Going concern financial position of the plan
The financial position of the plan on a going-concern basis is measured by comparing the actuarial value of assets to the actuarial liabilities assuming the plan is continuing for the long-term.
The following table outlines the results of the actuarial valuation performed as at Dec. 31, 2025. Comparative numbers as at Dec. 31, 2024 are also provided.
| Going concern financial position | 2025 | 2024 |
| Actuarial value of assets | $408,214,000 | $401,812,000 |
| Actuarial liability | $354,271,400 | $368,290,200 |
| Surplus (Deficit) | $53,942,600 | $33,521,800 |
| Funded Ratio | 115% | 109% |
Contribution and funding requirements
The plan last filed a valuation report with the regulators at Dec. 31, 2025. The valuation report has revealed a going concern surplus of $53,942,600 and therefore no special payments are required.
Hypothetical wind-up position of the plan
The Pension Benefits Act (Saskatchewan) requires the University to review whether the assets of the plan would be sufficient to cover the liabilities of the plan in the event of a plan wind-up and is required for transfer deficiency hold back when plan members leave the university. The following table outlines the wind-up position of the plan at Dec. 31, 2025. Comparative numbers as at Dec. 31, 2024 are also provided.
| Hypothetical wind-up financial position | 2025 | 2024 |
| Actuarial value of assets | $407,714,000 | $401,312,000 |
| Actuarial liability | $404,285,400 | $420,772,200 |
| Surplus/(deficit) | $3,428,600 | $(19,460,200) |
| Solvency ratio (assets/liabilities) | 101% | 95% |
Transfer deficiency requirements
Previously the plan's solvency ratio was below 100%, resulting in a transfer deficiency holdback for five years, upon termination from the plan. As the plan has attained a solvency ratio of 101% (determined in the last filed valuation at Dec. 31, 2025) it is no longer necessary to withhold a portion of lump-sum payments. Moving forward, 100% of lump-sum termination payouts will be provided upon termination, and this will remain in effect permitting the plan's solvency ratio remains above 100%.
Plan information
Plan Documents
Copies of the following documents are on file in the Pension office. They are available for inspection by any member of the plan during regular working hours by prior arrangements.
- plan text
- financial statements
- actuarial reports
- auditor’s report
Other Agents of the Plan
- Actuary: Aon, Saskatoon
- Investment Consultant: Aon, Calgary
- Custodian: CIBC Mellon
Pension Administration and Support
Room E140 Administration Building
University of Saskatchewan
105 Administration Place
Saskatoon, SK S7N 5A2
(306) 966-6633
(306) 966-2036
pension@usask.ca